Exploring Siding Loan Programs: A Comprehensive Guide
Siding loan programs are financial assistance programs designed to help homeowners cover the costs of installing or repairing the siding on their homes. These programs are typically offered by government agencies, non-profit organizations, or financial institutions.
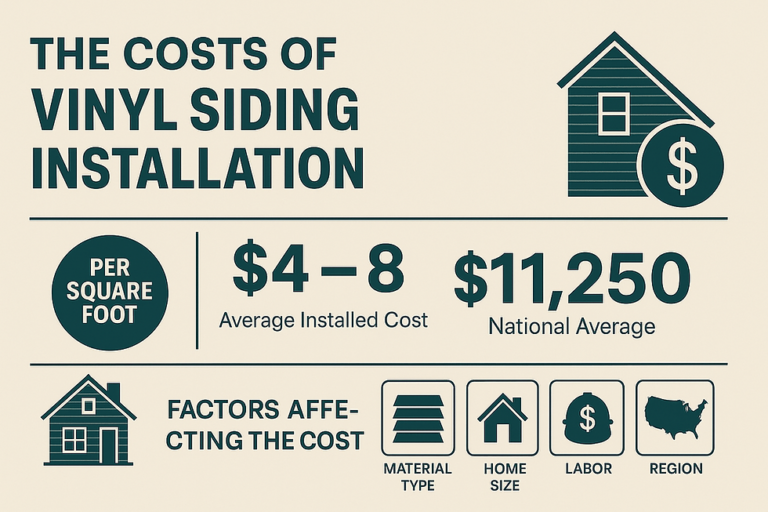
Siding loan programs aim to provide homeowners with access to affordable financing options for maintaining or upgrading the exterior of their homes. By offering low-interest rates or favorable repayment terms, these programs make it easier for homeowners to invest in the quality and durability of their siding.
When it comes to siding loan programs, there are several types available to homeowners looking to finance their siding projects. These programs vary in terms of eligibility criteria, interest rates, and repayment terms, so it’s essential to understand the differences before choosing one that suits your needs.
The FHA Title I loan program is designed to help homeowners make improvements to their properties, including siding replacement. These loans are backed by the federal government and have more lenient eligibility requirements compared to traditional loans.
A HELOC allows homeowners to borrow against the equity in their homes to fund home improvement projects, such as siding replacement. This type of loan typically has a variable interest rate and a draw period during which you can access funds as needed.
Personal loans can also be used to finance siding projects. These unsecured loans have fixed interest rates and a set repayment term, making them a straightforward option for homeowners who don’t want to use their home as collateral.
EEMs are specialized loan programs that allow homeowners to finance energy-efficient upgrades, including energy-efficient siding. These loans may offer lower interest rates or higher borrowing limits to incentivize energy-saving improvements.
FHA Title I Loan
Requires a good credit score but may be easier to qualify for compared to traditional loans.
HELOC
Requires a good credit score and a substantial amount of equity in your home.
Personal Loans
Require a good credit score and stable income to qualify.
EEMs
Eligibility criteria may vary by lender but often require a home energy assessment to determine the cost-effectiveness of the improvements.
PACE (Property Assessed Clean Energy) Financing
Allows homeowners to finance energy-efficient siding through an assessment on their property taxes.
Fannie Mae HomeStyle Renovation Loan
Offers financing for both the purchase and renovation of a home, including siding replacement.
VA Renovation Loan
Specifically designed for veterans, this loan program can finance home improvements, including siding upgrades.
To qualify for siding loan programs, individuals need to meet certain requirements and go through a specific application process. Improving eligibility for these programs can also be achieved through various strategies.
When choosing a siding loan program, it is crucial to evaluate various factors to ensure you select the best option that aligns with your financial needs and goals. Factors such as interest rates, repayment terms, and fees play a significant role in determining the overall cost and feasibility of the siding loan program.
Interest rates are a critical factor to consider when choosing a siding loan program. Lower interest rates can help you save money over the loan term, while higher interest rates can significantly increase the total cost of the loan. Compare interest rates from different lenders to find the most competitive offer.
Understanding the repayment terms of a siding loan program is essential to ensure that you can comfortably manage the monthly payments. Consider factors such as the repayment period, frequency of payments, and any flexibility in repayment options. Choose a loan program with repayment terms that fit your budget and financial situation.
In addition to interest rates, it is crucial to consider any fees associated with the siding loan program. Common fees include origination fees, prepayment penalties, and late payment fees. Be sure to factor in these fees when comparing loan offers to determine the total cost of borrowing.
To determine which siding loan program best suits your individual needs, consider your financial goals, budget, and repayment ability. Choose a loan program that offers competitive interest rates, favorable repayment terms, and minimal fees. Additionally, assess the lender’s reputation and customer service to ensure a smooth borrowing experience.
When utilizing siding loan programs, it is crucial to practice responsible borrowing to avoid financial pitfalls. By following these tips, you can effectively manage your siding loan repayments and steer clear of defaulting on payments.
Defaulting on your siding loan payments can have serious consequences, including:
What are the typical requirements to qualify for siding loan programs?
To qualify for siding loan programs, individuals usually need to have a good credit score, stable income, and meet specific lender requirements regarding the property in question.
How can one improve eligibility for siding loan programs?
Improving eligibility for siding loan programs can be done by improving one’s credit score, reducing existing debt, and ensuring timely payment of bills to showcase financial responsibility.
What are the consequences of defaulting on siding loan payments?
Defaulting on siding loan payments can lead to damaged credit scores, potential legal action from lenders, and even the risk of losing the property used as collateral for the loan.